The problem as it actually happens
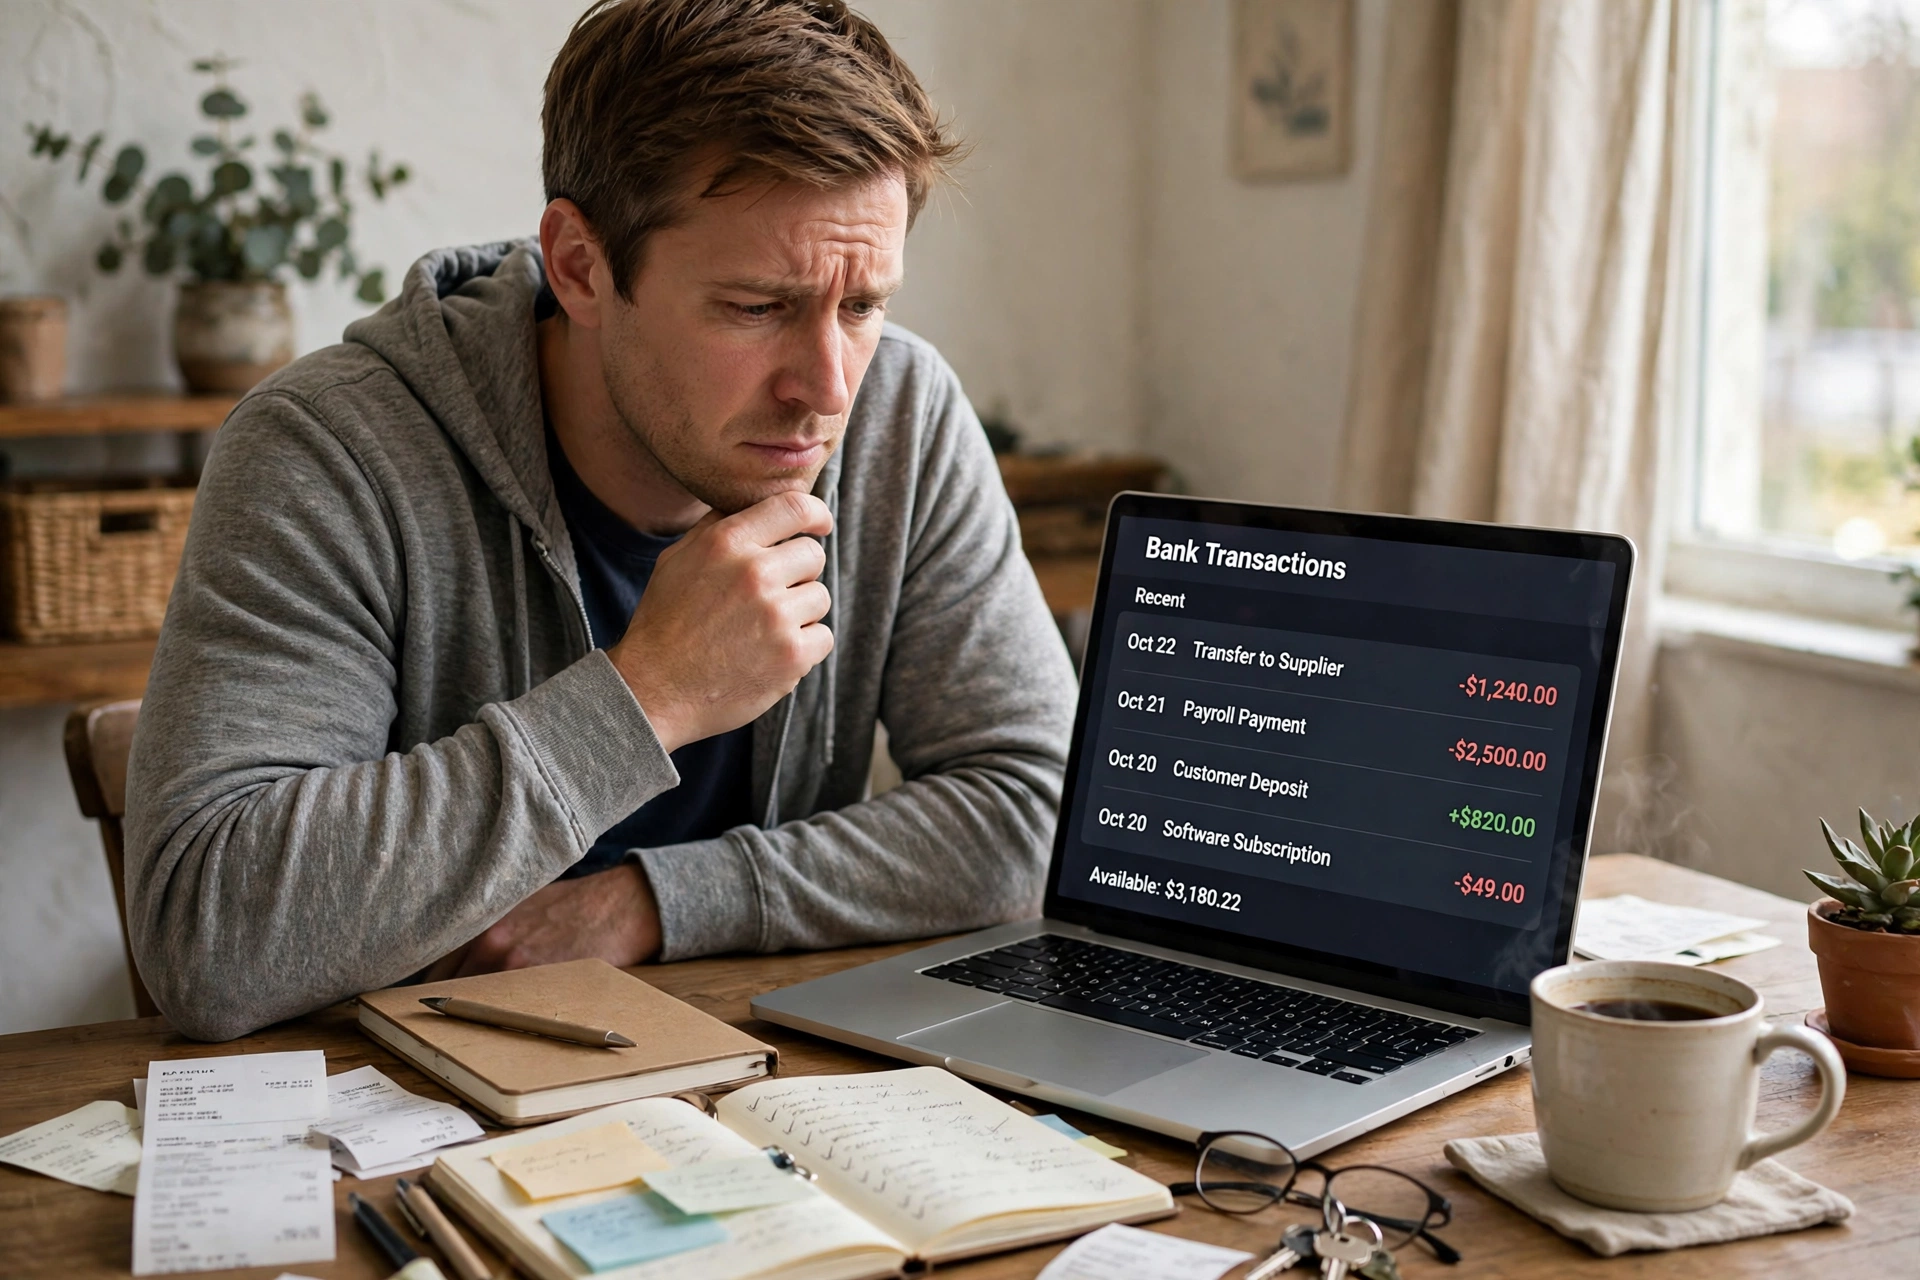
You send an invoice, the client pays, and you record the payment in QuickBooks. Then the bank feed downloads the same payment — and with one careless click, it is in your books twice. This is one of the most reported problems in QuickBooks community threads: reconnecting a bank, or re-categorizing an already-categorized transaction, brings the same money back into the review queue, and the second entry doubles the income.
Why it happens
The bank feed does not know what you already recorded. It only sees money moving in your bank account. QuickBooks gives you two very different buttons for that movement: Match, for money you already recorded (an invoice payment, a transfer, a payroll run), and Add, for genuinely new income or expense. Clicking Add on a payment that already exists creates a second, phantom sale. The same trap appears with transfers between your own accounts, and with payroll: categorizing a wage payment as a fresh expense instead of matching it to the payroll entry doubles that cost too.
What doubled transactions actually cost
Doubled income means an inflated profit figure, which means tax on money you never made twice. Doubled expenses understate profit and hide real costs. Either way, the books stop matching the bank statement, reconciliation fails, and month-end turns into a hunt for duplicates instead of a review of the business. Owners who discover this at tax time face amended figures and an accountant's cleanup bill.
The automation setup, step by step
- Set a match-first rule for the feed. Before anyone touches the review queue, the rule is: if this money was already recorded anywhere in QuickBooks — invoice, bill, payroll, transfer — it gets matched, never added.
- Use bank rules only for genuinely new, repeating items. A monthly software subscription or a regular supplier payment can be auto-categorized. Invoice payments and transfers must never be covered by a broad auto-add rule.
- Exclude, don't delete, true duplicates. When a reconnected bank re-downloads old transactions, exclude the duplicates from the feed so they never enter the ledger, and keep the original matched entries intact.
- Reconcile against the statement every month. Reconciliation is the safety net: if the QuickBooks balance and the bank statement disagree, a duplicate is sitting somewhere uncleared. Find it in the month it happened, not at year-end.
- Flag the exceptions for a person. Unmatched deposits over a set amount, transfers between accounts, and anything the rules cannot classify cleanly go to a weekly human review queue — they are never auto-added.
What stays with a person
Deciding whether an unmatched deposit is really new income, untangling a payroll double-count, and signing off the monthly reconciliation stay human. The automation sorts and matches the routine flow; a person owns the judgment calls and the final numbers. Money and tax always stay behind a human gate.
The weekly pass
Once a week, check three numbers: how many feed items were matched versus added, how many duplicates were excluded, and how many items are still sitting unreviewed. If "added" is climbing while invoices are also being recorded, the match-first rule is being ignored — retrain the habit before the next month's books inherit the error. Related reading: Why your marketplace payouts never match your sales and Automated monthly reports and bank reconciliation.
Next step
Want this running on your books? Book a free scoping call — we map your bank feed and reconciliation flow, then give you a fixed quote before anything is built. Start a request on the Bookkeeping automation page.